Simple vs Complex Trading System: Why Simple Wins
Every extra rule feels like safety. Mathematically it’s another way to overfit. Why simple trading systems usually outlive the clever, complicated ones.
Written for people who are not traders and never want to be. Almost everything you will read on this subject is written by someone with something to sell — so here are the questions people actually ask us, answered plainly, including the ones where the honest answer is don't.
Every extra rule feels like safety. Mathematically it’s another way to overfit. Why simple trading systems usually outlive the clever, complicated ones.
Four losses. Then eight. Then you start redesigning the whole strategy at 2am. Here’s how to tell if it’s actually broken or just having a statistically normal bad run.
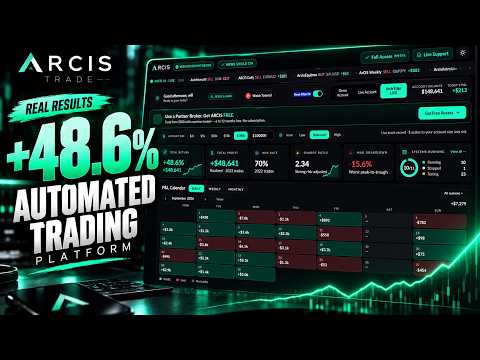
A short video walkthrough of the Arcis AI automated trading platform, showing how it works from the inside.
Why your position size decides whether a winning system actually compounds or just grinds. The quiet difference between fixed fractional and fixed lot.
Sharpe looks clean on a slide deck. But it can hide the exact risks that blow traders up. Here’s how to use it without kidding yourself.
Systems don’t usually explode. They fade. Here’s how to recognise trading system decay and decide when to retire a strategy before it buries your equity curve.
You don’t set risk per trade from the profit you want. You set it from the drawdown you can survive, then work backwards.
Sharpe looks clever: return per unit of volatility. The problem is what it quietly ignores — fat tails, path of returns, and how your equity curve actually bleeds.
Edges fade. The trick is knowing whether it’s normal drawdown or true system decay — and when to quietly pull a strategy from the lineup.
Why you slice winners, babysit losers, and blame the market. The maths of loss aversion, and how to structure your trading so your brain stops sabotaging your edge.
Most traders don’t kill bad systems. They kill good ones. Usually in a perfectly normal drawdown.
You don’t blow up because your entry is 3 pips off. You blow up because you stop following the plan. This is where trading psychology automation actually helps.
Everyone loves a high win rate. The account curve doesn’t. Here’s how win rate and risk-reward really trade off, and why expectancy is the only referee.
One backtest curve hides how bad the same trades could have felt. Monte Carlo simulation reshuffles them thousands of times and shows you the real range of pain.
Most traders argue about win rates and entries. The quiet killer sits in the background: how you resize after every trade.
Risk per trade isn’t about how fast you want to grow. It’s about how much drawdown you can survive when the losing streak that was “only on paper” finally turns up.
Everyone chases high win rates. The maths cares about expectancy. Here’s how win rate and risk-reward really trade off, and why a pretty equity curve can still hide a time-bomb.
Sharpe looks clean: return per unit of volatility. The trouble starts when you trust it. Here’s what it measures, and how it quietly hides your real risk.
Systems don’t blow up overnight. Most just quietly stop working. Here’s how to recognise trading system decay before it empties the account.
Slippage is the tiny gap between the price you wanted and the price you got. Once or twice it’s nothing. Across a thousand trades it can erase your entire edge.
A free 14-day demo. No card, no deposit, and your money never leaves your own broker account.